

Blogs
Analogue Meat Thermometer Market End-User Industry Analysis and Forecast Trends 2024-2033
By Arjun, 2026-09-18
Overview
The Analogue Meat Thermometer Market encompasses traditional temperature measurement devices used primarily in culinary and food safety applications. These devices are essential for ensuring precise cooking temperatures, thereby supporting food quality and safety standards across commercial kitchens, restaurants, and home cooking environments. Their core functionalities include providing accurate, real-time temperature readings through a dial or analog display, facilitating consistent results without reliance on digital components. As a fundamental tool, the analogue meat thermometer supports modern industries by enabling compliance with health regulations and enhancing culinary precision.
The market for analogue meat thermometers is critical in sectors where reliable, straightforward temperature monitoring is necessary. Its significance extends to food processing, catering, and retail outlets, where maintaining proper meat temperatures is vital for safety and quality assurance. The Analogue Meat Thermometer Market is driven by the ongoing demand for cost-effective, durable, and easy-to-use devices that do not depend on batteries or electronic components, making them a preferred choice in various operational settings.
Market Size and Growth
The current market value for analogue meat thermometers is estimated at approximately USD 250 million. Over the next decade, this figure is projected to reach around USD 350 million, reflecting a compound annual growth rate (CAGR) of approximately 4.5%. Growth drivers include increasing global food safety regulations, rising consumer awareness about food quality, and the ongoing preference for simple, reliable kitchen tools. Additionally, expanding foodservice and catering industries in emerging markets bolster demand for analogue temperature monitoring solutions.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2255
Key Drivers
- Rising food safety standards across industries
- Increasing demand for cost-effective, durable tools
- Growing adoption in food processing and catering
- Consumer preference for non-digital, straightforward devices
- Expansion of foodservice infrastructure in emerging economies
Restraints
- Limited features compared to digital alternatives
- Challenges in calibration and precision
- Regulatory restrictions on traditional devices
- Competition from advanced digital thermometers
- Cost constraints in low-budget segments
Segmentation
- By Type: Dial, Bimetallic
- By Deployment: Handheld, Wall-mounted
- By Enterprise Size: Small, Medium, Large
- By End User: Restaurants, Food Processing, Catering, Household
- By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market benefits from stringent food safety regulations and high culinary standards, fostering steady demand. Europe exhibits a mature market driven by culinary traditions and regulatory compliance. Asia-Pacific presents significant growth potential due to expanding foodservice sectors and rising disposable incomes. Latin America is gradually adopting analogue meat thermometers, with growth driven by increasing food safety awareness. The Middle East & Africa are emerging markets, where infrastructure development and regulatory enforcement are key growth factors.
Opportunities
- Expansion in emerging markets with growing food industries
- Integration with smart kitchen technologies
- Development of hybrid analogue-digital thermometers
- Adoption in industrial food processing facilities
- Innovation in materials for enhanced durability and accuracy
Key Companies
Taylor Precision Products, CDN, Polder, ThermoPro, OXO, Winco, Escali, Taylor, OXO, CDN, Taylor Precision Products, Food Timer Co.
Conclusion
The overall outlook for the Analogue Meat Thermometer Market remains positive, with steady long-term growth driven by safety standards and industry demand for reliable, low-cost temperature measurement tools. Its strategic importance in ensuring food safety and quality sustains its relevance across diverse sectors. As industries evolve, the market for analogue meat thermometers is poised for continued expansion, supporting industry standards and operational efficiencies well into the future.
Related Reports
Laser Beam Splitter Coatings Market , Size Share and Analysis | Report 2033
Pressurized Condensate Recovery System Market , Size Share and Analysis | Report 2033
High Capacity Closed Cycle Cryocooler Market , Size Share and Analysis | Report 2033
Gelatin Storage Tank Market , Size Share and Analysis | Report 2033
Hot Oil Systems Market , Size Share and Analysis | Report 2033
Dosing System For Ponds Market , Size Share and Analysis | Report 2033
Rubber Grinder Market , Size Share and Analysis | Report 2033
Industrial Hydraulic Servo Valve Market , Size Share and Analysis | Report 2033
Rolling Stock Suspension Systems Market , Size Share and Analysis | Report 2033
Wayside Lubrication System Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Analogue Oven Thermometer Market Insights on Regulatory Landscape and Environmental Impact 2024-2033
By Arjun, 2026-09-18
Overview
The Analogue Oven Thermometer Market encompasses devices designed to measure and display oven temperatures using traditional dial-based mechanisms. These thermometers are vital in ensuring precise cooking conditions, maintaining safety standards, and optimizing culinary outcomes across commercial and residential kitchens. Their core functionalities include accurate temperature readings, durability under high heat, and ease of use, supporting industries such as food processing, hospitality, and home appliance manufacturing.
The market for analogue oven thermometers continues to be essential for applications that require reliable, straightforward temperature monitoring. The Analogue Oven Thermometer Market plays a crucial role in supporting modern industries by providing cost-effective, low-maintenance solutions that do not depend on electronic components. Their simplicity and robustness make them indispensable in settings where electronic failures could lead to safety hazards or product quality issues.
Market Size and Growth
The current market value for analogue oven thermometers is estimated at around USD 150 million. Over the next decade, this figure is projected to reach approximately USD 250 million, reflecting a compound annual growth rate (CAGR) of about 5%. Growth is driven by increasing demand for traditional, dependable temperature measurement tools in both industrial and domestic sectors, alongside ongoing product innovation.
Factors such as rising food safety standards, the expansion of commercial kitchens, and the need for affordable temperature monitoring solutions are key growth drivers. Additionally, the enduring reliance on analogue devices in regions with limited access to advanced digital technology sustains market stability and expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2266
Key Drivers
- Growing demand for reliable, low-cost temperature measurement tools
- Increasing adoption in commercial kitchens and food processing plants
- Rising safety regulations requiring precise temperature control
- Preference for simple, maintenance-free devices in industrial settings
- Expansion of home baking and culinary activities
Restraints
- Competition from digital and smart thermometer alternatives
- Limited functionalities compared to electronic counterparts
- Regulatory standards favoring digital solutions in some regions
- Challenges in integrating analogue devices with modern automation systems
- Cost sensitivity in budget-constrained markets
Segmentation
- By Type: Dial thermometers, bimetallic thermometers
- By Deployment: Commercial, residential
- By Enterprise Size: Small businesses, large enterprises
- By End User: Foodservice, manufacturing, retail, household
- By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, demand remains steady driven by food safety standards and culinary trends emphasizing traditional cooking methods. Europe exhibits a preference for durable, easy-to-read analogue thermometers in professional kitchens and bakeries. Asia-Pacific shows rapid growth, fueled by expanding food processing industries and increasing consumer interest in home cooking. Latin America’s market growth is driven by rising restaurant chains and local food markets, while the Middle East & Africa focus on affordability and ruggedness for industrial applications.
Opportunities
- Growing adoption in emerging markets for cost-effective solutions
- Integration with digital systems for hybrid temperature monitoring
- Innovation in ergonomic design and durability
- Expansion into industrial sectors requiring high-temperature monitoring
- Development of calibration and maintenance services for analogue devices
Key Companies
Taylor Precision Products, Inc.
Polder Housewares
Oxo International Ltd.
Spring USA Inc.
Taylor Precision Products
KITCHENATICS
Winco
Berkley Square
Lavatools Inc.
Lacor
ThermoPro
Conclusion
The overall outlook for the Analogue Oven Thermometer Market remains positive, with long-term growth potential driven by the continued need for reliable, straightforward temperature monitoring solutions. As industries seek cost-effective and durable tools, analogue oven thermometers are poised to maintain their strategic importance across various sectors. The market’s stability and incremental growth underscore its significance in supporting safe and efficient culinary and industrial processes.
Related Reports
Infrared Thermal Imagers And Cores Market , Size Share and Analysis | Report 2033
Flow Through Style Cooler Market , Size Share and Analysis | Report 2033
Portable Bandsaw Mills Market , Size Share and Analysis | Report 2033
Industrial And Commercial Intelligent Lighting Market , Size Share and Analysis | Report 2033
Scanning Wavemeters Market , Size Share and Analysis | Report 2033
Ultra Low Temperature Vacuum Concentrator Market , Size Share and Analysis | Report 2033
Liquid Fermentation Tank Market , Size Share and Analysis | Report 2033
Vacuum Concentration Equipment For Food And Medical Market , Size Share and Analysis | Report 2033
Jam Concentration Equipment Market , Size Share and Analysis | Report 2033
Industrial Robot Servo Driver Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Cbl Cracking Furnace Market End-User Industry Analysis and Forecast Trends 2024-2033
By Arjun, 2026-09-18
The Cbl Cracking Furnace market pertains to industrial equipment used for the high-temperature conversion of carbon-based materials into valuable chemical products, primarily in the petrochemical and refining sectors. These furnaces play a critical role in breaking down complex hydrocarbons to produce feedstocks like synthesis gas and other chemical intermediates, which are essential for manufacturing plastics, fuels, and chemicals. Their purpose is to optimize the efficiency of chemical processes while maintaining safety and environmental standards, supporting modern industries' demand for sustainable and scalable production methods.
The market for Cbl Cracking Furnace is vital for enabling large-scale chemical manufacturing processes. It supports industries that rely on continuous, high-capacity operations. The core functionalities include precise temperature control, energy efficiency, and durability to withstand harsh operational conditions. The Cbl Cracking Furnace market is integral to advancing industrial productivity and innovation, especially as industries seek greener and more cost-effective solutions.
Market Size and Growth
The current market value for the Cbl Cracking Furnace industry is estimated at approximately USD 2.4 billion. Over the next decade, it is projected to reach around USD 4.8 billion, with a compound annual growth rate (CAGR) of about 8%. The growth is driven by increasing demand for petrochemical products, technological advancements in furnace design, and rising investments in refinery modernization. Expanding industrialization in emerging economies further fuels market expansion.
Key drivers include the global push for energy-efficient processes, stricter regulatory standards for emissions, and the need for higher throughput capacity. Rising adoption of automation and digital monitoring systems also enhances furnace performance, supporting sustained industry growth.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2219
Restraints
- High capital investment and operational costs
- Technical complexity of furnace maintenance
- Stringent environmental regulations
- Fluctuations in raw material prices
- Operational risks associated with high-temperature processes
Segmentation
- By Type: Batch, Continuous
- By Deployment: On-premises, Cloud-based
- By Enterprise Size: Large enterprises, SMEs
- By End User: Petrochemical, Refining, Chemical manufacturing, Others
- By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits mature demand driven by extensive refining capacity and technological upgrades. The region emphasizes energy efficiency and emissions reduction, influencing furnace adoption.
In Europe, strict environmental regulations and the push for cleaner production methods foster demand for advanced cracking furnace technologies. The industry focuses on modernization and compliance.
Asia-Pacific is the fastest-growing market, fueled by rapid industrialization, expanding petrochemical industries, and investments in infrastructure. Countries like China and India lead regional growth.
Latin America shows steady demand, primarily in Brazil and Mexico, with growth driven by refining expansion and chemical sector development.
Middle East & Africa are experiencing increased investments in refining capacity and petrochemical projects, aiming to meet regional energy needs and export demands.
Opportunities
- Adoption of AI and IoT for predictive maintenance
- Integration of renewable energy sources to reduce emissions
- Development of energy-efficient furnace designs
- Expansion in emerging markets with growing industrial bases
- Innovation in materials to enhance furnace lifespan and performance
Key Companies
Linde Group, Toyo Engineering Corporation, Outotec, Tenova, Fives Group, SMS Group, Kobe Steel, Hitachi, Technip Energies, Mitsubishi Heavy Industries, Alstom, Doosan.
Conclusion
The overall outlook for the Cbl Cracking Furnace market remains positive, with long-term growth potential driven by technological innovation and increasing industrial demand. As industries seek more sustainable and efficient processes, the strategic importance of advanced cracking furnace solutions will continue to rise. The market’s evolution offers significant opportunities for growth and technological leadership, underscoring its vital role in supporting modern chemical and petrochemical industries.
Related Reports
Facade Fastening Systems Market , Size Share and Analysis | Report 2033
Photonic Curing Systems Market , Size Share and Analysis | Report 2033
Xe Arc Lamps Market , Size Share and Analysis | Report 2033
Large Area Solar Simulators Market , Size Share and Analysis | Report 2033
Flash Solar Simulators Market , Size Share and Analysis | Report 2033
Steady State Solar Simulators Market , Size Share and Analysis | Report 2033
Agile Rf Synthesizers Market , Size Share and Analysis | Report 2033
Multi Photon Microscopes Market , Size Share and Analysis | Report 2033
Active Differential Probes Market , Size Share and Analysis | Report 2033
Pencil Probes Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Revenue Expansion and Market Outlook
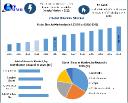
The Global Biscuits Market was valued at USD 135.56 billion in 2025 and is projected to reach approximately USD 190.75 billion by 2032 , expanding at a CAGR of 5% from 2025 to 2032 . The market is expected to maintain steady growth as biscuits remain a widely consumed packaged snack supported by convenience, affordability, long shelf life, and diverse flavors.
Demand is increasingly influenced by changing dietary preferences and product innovation. Health-oriented products such as sugar-free, low-calorie, multigrain, whole-grain, oat, high-fiber, vegan, and gluten-free biscuits are gaining attention. At the same time, premium and gourmet products are expanding the value of the category.
Access the Complete Report Sample : https://www.maximizemarketresearch.com/request-sample/26465/
Changing Consumer Preferences Reshape the Biscuit Industry
Biscuits have become an important component of the global packaged-food and snacking industry. Consumers are increasingly looking for products that combine convenience with nutritional benefits, while indulgent and premium formats continue to maintain demand.
The market is experiencing a shift toward healthy, clean-label, functional, plant-based, and diet-specific biscuits . Manufacturers are responding through reformulation, incorporating whole grains, natural ingredients, functional nutrients, and alternative formulations.
Premiumization is another important market trend. Gourmet cookies, artisanal biscuits, luxury packaging, exotic ingredients, chocolate coatings, and specialty flavors are attracting consumers seeking differentiated products. Millennials and working professionals are identified as important contributors to premium biscuit demand.
Modern retail and e-commerce are also improving accessibility. Supermarkets, hypermarkets, convenience stores, specialty retailers, and online platforms provide manufacturers with broader distribution opportunities. Digital promotions, influencer marketing, direct-to-consumer models, and online-exclusive products are further supporting category expansion.
However, manufacturers face pressure from fluctuations in the prices of wheat, sugar, palm oil, butter, and cocoa. Nutritional scrutiny, food-labeling requirements, intense competition, and alternative snacks such as granola bars, energy bars, protein products, baked chips, and artisanal snacks also create challenges.
Research Coverage and Analytical Framework
The MMR report uses 2025 as the base year and evaluates the market over the 2026–2032 forecast period , with historical data covering 2020–2025 . The study assesses the market through product, ingredient, distribution-channel, regional, and country-level analysis.
The report evaluates:
- Market size and revenue forecasts
- Product-type segmentation
- Ingredient-based segmentation
- Distribution-channel analysis
- Regional and country-level markets
- Market trends and dynamics
- Growth drivers and restraints
- Opportunities and challenges
- Consumer preferences and buying behavior
- Pricing and cost structure
- Competitive positioning
- Market-share assessment
- Porter’s Five Forces analysis
- PESTLE analysis
- Government support and industry developments
- Strategic insights
Request the Detailed Market Report : https://www.maximizemarketresearch.com/request-sample/26465/
Regional Consumption Patterns and Growth Centers
Asia Pacific dominated the Global Biscuits Market in 2025 and is identified as the fastest-growing regional market. Strong demand across India, China, Indonesia, Vietnam, and Japan , combined with large populations, urbanization, expanding retail infrastructure, and changing consumption patterns, supports regional growth.
India represents an important consumption market, with demand spanning traditional tea-time biscuits as well as digestive, plant-based, and gluten-free products. Growing e-commerce penetration and convenient on-the-go packaging are also supporting market accessibility in the region.
Europe held the second-largest share of the global market. The region benefits from an established biscuit and cookie consumption culture and strong demand for organic, clean-label, vegan, gourmet, artisanal, and specialty products.
The report also evaluates North America, Middle East & Africa, and South America , with country-level coverage across major markets.
Product, Ingredient and Distribution Segmentation
The Global Biscuits Market is segmented by product type, ingredients, distribution channel, and region .
By Product Type , the market includes:
- Plain Biscuits
- Cookies
- Sandwich Biscuits
- Wafer Biscuits
- Others
Cookies dominated the market in 2025 and are expected to maintain their leading position through the forecast period. Their broad flavor range, indulgent positioning, premium variants, and suitability for everyday snacking contribute to strong consumer demand.
Plain biscuits remain important in price-sensitive markets, particularly across Asia and Africa. Sandwich biscuits benefit from youth-oriented products and cream-filled varieties, while wafer biscuits are gaining traction in premium and gifting categories.
By Ingredients , the market comprises:
- Wheat-based Biscuits
- Oat-based Biscuits
- Multigrain Biscuits
- Protein-fortified Biscuits
- Organic Biscuits
Wheat-based biscuits represented the leading ingredient segment in 2025 because of their broad availability, affordability, and established consumer acceptance. Oat-based, multigrain, protein-fortified, and organic products are gaining attention as consumers increasingly seek nutritional and functional alternatives.
By Distribution Channel , the market covers:
- Supermarkets & Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
The expansion of modern retail and online commerce is increasing product availability while providing manufacturers with additional channels for niche, premium, and diet-specific biscuit products.
Competitive Positioning Across Global Biscuit Manufacturers
The Global Biscuits Market is highly competitive, comprising multinational corporations, regional manufacturers, private-label companies, and emerging niche brands. Competition is shaped by product innovation, pricing, distribution reach, brand strength, packaging, and the ability to respond to evolving consumer preferences.
Key companies covered by the MMR report include:
- Nestlé
- Parle Products
- Britannia Industries
- ITC Sunfeast
- Mondelez International
- Ferrero Group
- Kellogg’s
- General Mills
- PepsiCo
- Lotus Bakeries
- United Biscuits
- Burton’s Biscuit Company
- Pladis Global
- Danone
- Bahlsen GmbH
- Walkers Shortbread Ltd
- Annas Pepparkakor
- Arcor
- Gullón
- Dr Gerard
- Chipita
- Yildiz Holding
- Orion Confectionery
- Lotte Confectionery
- Tunnock’s
- Haitai Confectionery
- Mayora Indah
- Bourbon Corporation
- Sanritsu Confectionery
- Campa
Recent product activity highlighted by the report includes Mondelez's Oreo Thins expansion, Nestlé's plant-based biscuit initiative, and Britannia Industries' NutriChoice Seeds Biscuits launch. These developments reflect the industry's focus on premiumization, plant-based products, and health-oriented formulations.
Get a Free Preview of Market Insights : https://www.maximizemarketresearch.com/request-sample/26465/
Key Questions Addressed by the Market Report
- What was the Global Biscuits Market size in 2025?
The market was valued at USD 135.56 billion in 2025 . - What is the projected market value by 2032?
The market is expected to reach approximately USD 190.75 billion by 2032 . - What CAGR is expected during the forecast period?
The market is projected to grow at a 5% CAGR from 2025 to 2032 according to the market-size summary. - Which region dominated the market in 2025?
Asia Pacific dominated the market in 2025 and is also identified as the fastest-growing regional market. - Which product type held the leading position?
Cookies dominated the product-type segment in 2025.
Report Components and Strategic Insights
The Global Biscuits Market report provides a detailed assessment of market development and competitive conditions through 2032. Its principal deliverables include:
- Global market size and forecast through 2032
- Historical market analysis from 2020–2025
- Forecast assessment for 2026–2032
- Product-type analysis
- Ingredient-level segmentation
- Distribution-channel assessment
- Regional and country-level analysis
- Market drivers, restraints, opportunities, and challenges
- Consumer preference and buying-behavior analysis
- Pricing and production-cost assessment
- Competitive landscape
- Company benchmarking
View More Reports :
Wedding Services Market https://www.maximizemarketresearch.com/market-report/wedding-services-market/229647/
Running Shoes Market https://www.maximizemarketresearch.com/market-report/running-shoes-market/193998/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us :
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
AI consulting and AI development serve different purposes. AI consulting helps businesses decide what to build, why it matters and how to approach it. AI development turns those decisions into working software, integrations and systems.
Choosing the right service depends on where your business is in its AI journey.
AI Consulting vs AI Development
| AI Consulting | AI Development | |
|---|---|---|
| Main focus | What to build and why | How to build and run it |
| Typical deliverables | AI assessment, roadmap, use cases, governance and business case | Models, APIs, integrations, pipelines and monitoring |
| Typical team | Strategists, architects and domain specialists | Developers, ML engineers, data engineers and MLOps |
| Typical duration | 4–12 weeks | 3–12 months, then ongoing |
| Success measure | Clear, practical decisions | A working and adopted system |
The key difference is simple: consulting addresses uncertainty, while development addresses execution.
When Do You Need AI Consulting?
AI consulting may be suitable when:
- You have several AI ideas but do not know which to prioritise.
- Your board wants a clear plan for an AI budget.
- You are unsure whether your existing data can support an AI project.
- Previous AI pilots did not reach production.
- You need governance for regulatory or compliance requirements.
- Suppliers are providing very different project estimates.
If you cannot yet describe what the system needs to do, an assessment can help define the specification before development begins.
When Do You Need AI Development?
AI development is more appropriate when:
- You have a clearly defined business process to improve.
- Your proof of concept has already met its targets.
- You have a strategy but no working system.
- You have a model that works but has not been deployed.
- Your main challenge is integration with existing systems.
- You have the knowledge to define the project but need additional development capacity.
A Practical AI Project Sequence
For businesses that need both services, a practical approach is:
- Assessment: Review data, use cases and costs.
- Proof of concept: Test the priority use case against agreed criteria.
- Production build: Develop, integrate and monitor the system.
- Ongoing operation: Measure performance and extend the solution where needed.
Consulting is more prominent during the first two stages, while development becomes the main focus during production and ongoing operation.
When Can You Skip AI Consulting?
If you have one clearly defined problem, accessible data, an existing baseline and an internal owner, you may be able to move directly into development.
Typical UK AI Project Costs
| Service | Typical UK Cost |
|---|---|
| Readiness assessment | £12,000–£35,000 |
| Strategy and governance | £40,000–£120,000 |
| Proof of concept | £15,000–£50,000 |
| Production build | £60,000–£250,000 |
| Ongoing operation | 15–25% of build cost annually |
Actual costs depend on project scope, data, integrations and operational requirements. Ongoing costs should also be discussed before development starts.
How to Choose an AI Partner
If you are considering a company that provides both consulting and development, ask:
- Will you recommend buying an existing solution where appropriate?
- Can you demonstrate systems that remain in production?
- Who will actually work on the project?
- What happens if the assessment says the project should not proceed?
These questions can help separate genuine consultancy from a strategy phase designed mainly to lead into development.
A Simple Decision Test
Ask yourself three questions:
- Can you name the process you want to improve?
- Do you know its current cost or error rate?
- Is someone responsible for the resulting system?
If all three answers are yes, you may be ready for development. If not, a focused AI assessment can help clarify the next step.
Businesses looking for both services can start with AI consulting services and move into AI development services when the specification is ready.
Frequently Asked Questions
Can we handle AI consulting internally and outsource development?
Yes. This can work when your internal team understands the business process and data, with external support used to challenge the assessment before development.
How long should AI consulting take?
A focused assessment generally takes 4–6 weeks , while broader strategy and governance work may take 8–12 weeks .
Is AI development just software development?
Not quite. AI projects also require data engineering, performance monitoring and ongoing management as data and model behaviour change.
What if we already have an AI strategy?
Have it independently reviewed rather than automatically commissioning another full strategy. This can confirm whether its assumptions and priorities remain valid.
Should we hire an internal AI team or use an external partner?
Many organisations use a combination: permanent internal ownership supported by external specialists for initial development and specialist technical work.
Strategic Trends and Commercial Opportunities in the Global Polymer Substrates Market
Market Landscape and Core Challenges
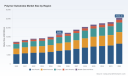
The worldwide polymer substrates market has demonstrated robust expansion over the past half-decade, evolving from a steady growth trajectory into a dynamic sector shaped by technological convergence and shifting industrial priorities. Valued at approximately $12.25 billion in 2020, the market reached an estimated $16.45 billion by 2025, reflecting a compound annual growth rate of 6.42 percent through the forecast period extending to 2032. This expansion is not merely a function of volume but reflects deepening penetration across high-value electronics, energy infrastructure, and security applications. The market structure remains moderately fragmented, with the top three participants capturing just over 32 percent of total revenue and the top five firms approaching 48 percent. Such concentration levels indicate a landscape where scale advantages exist but are not insurmountable, leaving room for specialized players to compete on performance, regional proximity, or application-specific engineering.
Despite the positive trajectory, the industry stands at a critical inflection point defined by three interlocking challenges. First, raw material volatility has transitioned from a periodic disruption to a structural stressor. Feedstocks such as ethylene, propylene, and purified terephthalic acid form the backbone of mainstream polymer films, yet their pricing can swing by as much as 25 percent within a single year. This unpredictability compresses margins for manufacturers who operate on fixed-price contracts or lack the agility to pass costs downstream. Second, regulatory tightening is reshaping compliance economics. Recent restrictions on methylene chloride as a bonding agent for acrylic and polycarbonate substrates, alongside the phase-out of hexavalent chromium in plastic plating, have elevated compliance expenditures by roughly 18 to 25 percent for treatment facilities. These rules do not merely add administrative burden; they force retooling, process redesign, and verification protocols that disproportionately affect mid-tier producers. Third, the rapid proliferation of advanced display architectures and flexible circuit designs is raising performance thresholds. Suppliers must now balance thermal stability, optical clarity, dielectric consistency, and mechanical durability within thinner form factors, creating a technical barrier that favors companies with integrated R&D and application-specific formulation capabilities.
For executives evaluating market entry, expansion, or procurement strategies, these dynamics signal a shift from volume-driven competition to value-driven differentiation. The organizations that navigate this phase successfully will be those that treat feedstock risk, regulatory adaptation, and performance specification as interconnected strategic variables rather than isolated operational concerns.
Key Drivers Reshaping the Market
Technological innovation remains the primary engine of market evolution. The transition from rigid to flexible electronic architectures has elevated polymer substrates from passive carriers to active enablers of device performance. Polyimide and polyester films, for instance, are no longer evaluated solely on mechanical flexibility; they are scrutinized for thermal endurance, coefficient of thermal expansion matching, and compatibility with lamination and etching processes. Meanwhile, newer thiol-based optical polymer films and engineered adhesives are addressing long-standing trade-offs between transparency, adhesion, and reworkability in display manufacturing. These material advances are not incremental; they are unlocking form factors that were previously uneconomical or technically unfeasible, particularly in ultra-thin wearable devices and foldable display panels.
Policy and regulatory frameworks are acting as a second, equally powerful driver. Environmental mandates are accelerating the redesign of both materials and processing pathways. Restrictions on certain solvents and heavy-metal plating compounds are pushing manufacturers toward water-based adhesives, low-volatile organic compound formulations, and alternative surface treatments. While compliance costs have risen, these regulations are also creating a structural advantage for firms that have already invested in cleaner process architectures. In regions where electronics waste directives and chemical safety standards are tightening, suppliers with verified environmental compliance are finding preferential access to premium contracts, particularly with multinational OEMs that face their own downstream reporting obligations.
Demand-side behavior is undergoing a parallel transformation. Consumer electronics manufacturers are racing to reduce device weight and thickness while maintaining durability, a push that directly increases the share of flexible printed circuits and OLED display applications within the substrate mix. Simultaneously, the expansion of photovoltaic installations and the electrification of automotive systems are driving requirements for substrates that can withstand UV exposure, moisture ingress, and thermal cycling over extended service lives. Medical device designers are adopting polymer films for imaging substrates, diagnostic patches, and sterilization-compatible housings, valuing their biocompatibility and dimensional stability. These application shifts are not isolated; they are converging on a common requirement set that favors materials with tunable mechanical properties, predictable dielectric behavior, and reliable supply continuity.
Supply chain and cost structure dynamics complete the driver set. Regional production footprints are being recalibrated as companies respond to freight volatility, tariff uncertainty, and the desire for shorter lead times. Price adjustments on engineered materials and polymer dispersions have become more frequent, reflecting both upstream feedstock conditions and the costs of maintaining compliance-ready facilities. In this environment, procurement strategies that once prioritized unit price are increasingly incorporating total cost of ownership metrics, including yield loss, rework rates, logistics resilience, and regulatory risk. Suppliers that can offer consistent lot-to-lot quality, transparent sourcing, and application engineering support are capturing disproportionate value, even when their headline pricing is higher.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of global materials giants, regional specialists, and application-focused innovators. DuPont continues to leverage its polyimide heritage, particularly its Kapton legacy, to serve flexible electronics, display, and high-temperature automotive applications. Its positioning emphasizes long-standing process knowledge, broad qualification history with major OEMs, and the ability to supply substrates that meet stringent thermal and mechanical specifications. 3M complements this profile with a focus on optical clarity, durability, and precision film engineering, targeting display and printed electronics applications where surface quality and dimensional consistency are decisive. Toray and Teijin, together with Sumitomo Chemical and Mitsubishi Chemical, form a strong Asian manufacturing core that combines polyester and polyimide expertise with deep integration into regional electronics and display supply chains. Their advantage lies in scale, proximity to panel and circuit manufacturers, and the ability to tailor film grades to specific lamination and etching workflows.
Beyond mainstream electronics, a distinct competitive cluster has emerged around security and currency substrates. Companies such as CCL Secure, De La Rue, Landqart, and Giesecke+Devrient have built specialized capabilities that combine biaxially oriented polymer films with integrated security features, authentication layers, and printing compatibility. De La Rue, for example, operates an integrated model that couples substrate production with security feature embedding and print readiness, reducing coordination friction for central bank issuance programs. The recent adoption of Q&T Hi-Tech Polymer's domestic PolySecure substrate in Vietnamese currency illustrates how regional producers can capture sovereign issuance cycles by offering localized supply, cost competitiveness, and alignment with national printing infrastructure. This segment demonstrates that polymer substrates are not a monolithic market; competitive advantage often comes from mastering a specific application's certification, security, and logistics requirements rather than competing purely on film thickness or polymer grade.
The market's evolution is being shaped by simultaneous consolidation and specialization. Larger materials groups are acquiring or partnering to secure feedstock access, expand high-performance film portfolios, and broaden regional coverage. At the same time, new entrants are carving out positions through targeted innovations such as thiol-based optical films, RF and microwave-grade substrates, and next-generation display-compatible architectures. Recent pricing actions by major producers highlight the tension in the current environment: several global manufacturers announced material price increases effective in early 2026, citing raw material and production costs. These adjustments are not merely tactical; they reflect a structural recalibration as firms protect margins amid feedstock volatility and compliance investment. Buyers are responding by diversifying supplier bases, locking in longer-term agreements with performance guarantees, and shifting certain certifications in-house to reduce dependency on single-source qualification cycles.
For strategists, the clearest signal is that differentiation is increasingly earned at the intersection of material science, regulatory readiness, and application engineering. Companies that can demonstrate measurable improvements in yield, thermal reliability, or processing speed are winning premium placements, while those competing solely on commodity pricing are facing progressive margin erosion.
Future Trends and Commercial Implications
Several trajectories are likely to define the next three to five years. The first is the continued migration of polymer substrates into higher-complexity electronic architectures. As foldable displays, wearable sensors, and advanced flexible circuits move from premium niches toward broader adoption, substrates will need to satisfy tighter tolerances for dimensional stability, dielectric uniformity, and long-term fatigue resistance. This trend will create opportunities for suppliers that offer co-engineered film systems, including adhesives, cover layers, and surface treatments optimized for specific assembly processes. Manufacturers that provide application engineering support and process validation will capture more value than those selling bare film alone.
Ceramic Substrate Market
A second trend is the deepening influence of regulatory and sustainability mandates on material selection. Chemical restrictions and emissions expectations are unlikely to plateau; they will expand in scope and enforcement intensity. This will favor substrates and processing routes that reduce solvent use, lower heavy-metal dependency, and improve recyclability or end-of-life handling. Companies that proactively redesign offerings around compliance-forward chemistries will gain preferential access to OEMs facing their own procurement standards and public reporting requirements. In parallel, procurement teams will increasingly evaluate suppliers on environmental documentation, traceability, and audit readiness, making these capabilities a commercial differentiator rather than a back-office function.
Worldwide Polished Substrates Market
A third trend is the regional reconfiguration of supply networks. Freight instability, lead-time sensitivity, and currency exposure are prompting buyers to diversify across geographies and to favor suppliers with local or near-local production capacity. This shift creates openings for regional specialists that can deliver reliable volume, faster response cycles, and lower logistics risk, even if they lack the global footprint of multinational incumbents. The resulting landscape will reward agility, transparent communication, and the ability to manage qualification and certification efficiently across multiple jurisdictions.
These trends carry both opportunity and uncertainty. Demand growth is likely to remain positive, but the distribution of value will tilt toward firms that can absorb feedstock and compliance risk without sacrificing performance consistency. Buyers who treat substrates as strategic components rather than commoditized inputs will be better positioned to manage cost volatility and technology transitions.
Actionable Guidance for Decision-Makers
Manufacturers should prioritize application-specific film development and process integration over broad commodity expansion. Investing in co-engineered substrate systems, qualification support, and consistent lot quality will strengthen customer retention and protect margins against price competition. Where feedstock exposure is significant, long-term sourcing agreements, hedging strategies, and alternative polymer pathways should be evaluated to reduce vulnerability to annual volatility swings.
Investors should focus on companies with defensible technical moats, regulatory readiness, and diversified application exposure across electronics, energy, security, and medical uses. Business models that combine material capability with service layers such as engineering support, certification assistance, and regional supply resilience are better positioned to sustain pricing power. Caution is warranted where growth depends primarily on volume throughput without corresponding differentiation in performance or compliance.
PW Consulting
Procurement and sourcing leaders should expand evaluation criteria beyond unit cost to include total cost of ownership, yield impact, lead-time reliability, and regulatory documentation. Multi-supplier strategies, paired with clear performance specifications and shared qualification data, can reduce single-point failures while maintaining competitive tension. Early engagement with suppliers on upcoming material or regulatory changes will also shorten adaptation cycles and lower the risk of production disruption.
For organizations seeking deeper segmentation data, company-level positioning detail, and customized scenario planning across regions and application verticals, the full research report provides expanded datasets and tailored analysis. The complete study maps growth trajectories by material type, application, and region, alongside competitive profiling and procurement risk frameworks, offering a practical reference for strategy development and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Polymer Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Military Protective Eyewear Market’s 6.78% CAGR Reshapes Procurement Strategy
By PW Consulting, 2026-09-18
The Global Military Protective Eyewear Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
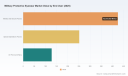
The worldwide military protective eyewear market has demonstrated sustained momentum, evolving from a niche procurement category into a strategically significant segment of defense logistics and soldier modernization. Between 2020 and 2025, market revenue expanded steadily, reflecting consistent procurement cycles, incremental capability upgrades, and the widespread institutionalization of eye protection as a baseline combat requirement. This upward trajectory is projected to persist through the 2026–2032 forecast horizon, supported by a compound annual growth rate that underscores the segment's resilience and strategic relevance. The market's scale now positions protective eyewear as an integral component of force readiness rather than an ancillary accessory, with procurement volumes increasingly tied to fleet-wide modernization initiatives and coalition interoperability standards.
Despite this favorable backdrop, industry participants navigate a complex operating environment defined by several structural tensions. First, the dual mandate of meeting rigorous ballistic performance thresholds while maintaining ergonomic comfort, optical clarity, and environmental adaptability creates a persistent engineering balancing act. Specifications such as MIL-PRF-32432 and MIL-PRF-31013 establish demanding impact-resistance criteria, requiring products to withstand high-velocity fragments without compromising field usability. At the same time, the Authorized Protective Eyewear List framework introduces a procurement dynamic where approval status, logistical compatibility, and mission-specific suitability directly influence adoption rates. Manufacturers must therefore align technical performance with procurement workflows and user acceptance patterns, a challenge that intensifies as operational environments grow more varied.
Worldwide Military Protective Gear Market
Second, supply chain and cost structures introduce volatility that reverberates across the value chain. The market's concentration profile, with a notable share held by a relatively small group of established players, highlights both the barriers to entry and the operational scale required to compete effectively. Splitting production across specialized component sourcing, optical coating, frame manufacturing, and stringent quality assurance means that raw material fluctuations, logistics disruptions, or certification delays can quickly translate into margin compression. For buyers, this translates into procurement cycles that must account for lead-time management and qualification timelines; for manufacturers, it underscores the importance of resilient sourcing strategies and modular design architectures that can accommodate supply variability without sacrificing compliance.
Third, the market sits at a transition point driven by evolving threat profiles and changing procurement philosophies. Modern combat scenarios increasingly involve asymmetric threats, urban engagements, and multi-domain operations where fragmentation, laser-based systems, and environmental hazards coexist. This shifts the priority from baseline protection toward integrated capability sets that can adapt across missions. At the same time, budget cycles and multinational procurement programs favor standardization, interoperability, and lifecycle cost considerations. Companies that can demonstrate not only compliance but also operational value—reduced injury incidence, improved situational awareness, clearer optics under varied lighting, and streamlined maintenance—are better positioned to secure sustained demand in an environment where procurement decisions increasingly weigh total value rather than unit price alone.
Key Drivers Reshaping the Market
Several interrelated forces are shaping the direction of the military protective eyewear market, each reinforcing the others and creating distinct implications for product strategy, procurement planning, and competitive positioning.
Technological innovation continues to redefine what protective eyewear can deliver in the field. The dominant product category remains ballistic spectacles, reflecting the enduring requirement for high-velocity impact and fragment protection in operational settings. Yet the performance envelope is expanding well beyond baseline impact resistance. Photochromic and polarized lens technologies, for example, address real-world visibility challenges by adapting to changing light conditions and reducing glare without sacrificing ballistic integrity. Anti-fog coatings, moisture-management frame designs, and prescription-compatible configurations further bridge the gap between protection and sustained operational usability. These enhancements are not cosmetic; they respond directly to the practical demands of extended deployments, fast-paced engagements, and environments where visual performance influences both safety and mission effectiveness. As a result, differentiation increasingly emerges from the integration of multiple functional capabilities rather than from a single standout feature.
Worldwide Military Wearable Market
Policy and regulatory frameworks act as both gatekeepers and accelerators. In the U.S. context, the requirement to meet MIL-PRF standards ensures a high floor for performance, while the Authorized Protective Eyewear List provides a procurement mechanism that shapes which products gain field traction. The existence of a formal approval pathway creates predictability for suppliers that invest in compliance, but it also raises the stakes for entry, since qualification is a prerequisite for large-scale adoption in many programs. Outside the U.S., comparable standards and multinational procurement expectations are increasingly influencing product development priorities. ANSI/ISEA Z87.1 remains a widely recognized baseline, but military applications often exceed that threshold through additional ballistic, optical, and environmental performance requirements. This layered standards environment rewards manufacturers that can navigate both commercial safety benchmarks and defense-specific certification regimes, while also aligning product roadmaps with anticipated specification updates.
On the demand side, shifting procurement behavior and user expectations are altering the value proposition. Rising global defense expenditures and soldier modernization programs continue to drive demand for advanced military protective eyewear across major NATO and allied forces. This is not merely a volume story; it reflects a broader modernization philosophy in which individual equipment is evaluated as part of an integrated soldier system. Procurement teams increasingly look for solutions that support interoperability, reduce logistical complexity, and perform reliably across training and combat conditions. End-user preferences also play a growing role, as operators favor gear that is comfortable, lightweight, and adaptable without compromising protection. When products are perceived to enhance mission readiness—through better optics, fewer field adjustments, or seamless compatibility with helmets and other tactical equipment—adoption momentum strengthens accordingly.
Supply chain and cost dynamics form the fourth major driver. The market's structure favors organizations that can manage complexity at scale, balancing component sourcing, manufacturing precision, and qualification rigor. Recent activity illustrates how companies are responding to these pressures through contract wins, certification milestones, and new product introductions. Several manufacturers have secured framework agreements and specialized program awards that underscore the importance of reliable supply and proven compliance. At the same time, the launch of newer eyewear systems at major industry events signals continued investment in capability upgrades and platform compatibility. These developments point to a competitive environment in which operational reliability, certification readiness, and program execution are becoming as important as product features alone. Cost management is therefore not just a procurement concern but a strategic capability: companies that can maintain performance and compliance while controlling total cost of ownership are better equipped to win multi-year programs and defend margins in a market that rewards consistency.
Competitive Landscape and Leading Strategies
The competitive environment in military protective eyewear is defined by a small group of entrenched manufacturers that combine technical capability, program experience, and established relationships with procurement authorities. Market concentration reflects the realities of certification, scale, and long-cycle defense procurement, but it also leaves room for differentiation through product architecture, mission-specific configuration, and execution reliability. Several companies have built leading positions by aligning their offerings with the dual demands of ballistic performance and field usability, while also pursuing strategic moves that extend their reach across programs and operating environments.
Revision Military has maintained a strong profile as a specialist in ballistic and performance eyewear for military and tactical users. Its portfolio spans multiple systems designed to meet rigorous standards and serve diverse operator requirements, and recent developments highlight a dual focus on contract execution and product qualification. The company's activities in 2025, including supplying special forces with established eyewear systems and securing national stock number recognition for a goggle kit for U.S. military use, illustrate how qualification milestones and targeted program wins can reinforce market presence. An earlier framework contract with the NATO Support and Procurement Agency points to a longer-term strategy centered on multinational relevance and supply chains that can support coalition requirements. This combination of product breadth, certification progress, and institutional engagement positions the company to compete where interoperability and proven compliance matter.
Gentex Corporation occupies a distinct position through its emphasis on advanced eyewear and optics for both ground forces and aircrew. Its product portfolio includes ballistic eyewear systems and laser eye protection solutions, and recent program activity demonstrates the company's ability to engage with specialized requirements. The launch of an updated ballistic eyewear system at a major industry showcase signaled continued investment in platform-compatible design and field-oriented performance. Equally notable was the award of a U.S. Air Force aircrew laser eye protection program, which reflects demand for mission-specific optical solutions that address distinct threat environments. This blend of ground and aircrew focus suggests a strategy oriented around capability breadth and program specialization, where value is created not only through protection but also through optical performance tailored to specific operational roles.
Other established players contribute to a competitive field shaped by different strengths. ESS Eye Pro emphasizes high-performance impact protection for military, law enforcement, and tactical use, with a product set built around ballistic goggles, sunglasses, and eyeshields that meet recognized safety standards. Oakley Standard Issue leverages brand recognition and optical engineering to supply ballistic sunglasses and tactical eyewear designed for helmet compatibility and clarity, with products aligned to military procurement specifications. Wiley X focuses on tactical and ballistic-rated eyewear featuring high-velocity impact protection and interchangeable lens systems, an approach that supports adaptability across environments. Bolle Safety and uvex bring European manufacturing heritage and defense-adjacent safety expertise, with product lines and industry affiliations that reinforce their relevance in multinational and special-forces contexts. American Optical draws on a long supply history with the U.S. military and a specification-driven approach to military eyewear, reinforcing a positioning rooted in proven pedigree and compliance orientation.
What distinguishes these leaders is not only product performance but strategic positioning. Leading manufacturers tend to pursue a combination of certification readiness, program execution, and mission-specific configuration. They invest in meeting or exceeding military specifications, while also developing product architectures that simplify field use, maintenance, and compatibility with other equipment. The result is a market in which success increasingly depends on the ability to deliver consistent compliance, reliable supply, and practical operability rather than on a single breakthrough feature. At the same time, the landscape appears to be evolving along multiple axes. Consolidation pressure exists where scale, qualification expertise, and program relationships create advantages for larger or well-connected players. At the same time, differentiation remains possible through specialized solutions, such as laser protection for aircrew, advanced lens technologies for varied lighting conditions, or configurations optimized for special operations. New entrants face meaningful hurdles, but niche positioning around particular mission needs, coalition procurement pathways, or complementary technologies can create viable avenues for growth.
Forward Outlook: Trends and Commercial Implications
Looking ahead across the 2026–2032 period, several trends are likely to shape the market's direction and create distinct commercial implications. The first is the continued shift from baseline protection to integrated capability. As operational environments become more complex, demand will increasingly favor eyewear that combines ballistic resilience with optical versatility, environmental durability, and compatibility with broader soldier systems. Products that can reduce the number of separate accessories operators must carry, or that support rapid adaptation across training and combat conditions, are well placed to capture attention in modernization programs. Commercial opportunity here lies in modular designs, advanced lens technologies, and configurations that simplify logistics while preserving performance across mission profiles.
A second trend is the growing importance of specialized protection segments within the broader market. Laser eye protection for aircrew and other specialized roles illustrates how threat-specific requirements can create focused demand streams that reward targeted development and program specialization. These segments may not dominate total volume, but they often carry higher value intensity and stronger differentiation potential because they address distinct operational needs. Manufacturers that cultivate capability depth in these areas can build defensible positions, particularly where certification pathways and program relationships reinforce repeat engagement. The commercial implication is that companies should evaluate not only overall market growth but also the relative attractiveness of sub-segments where technical complexity and mission specificity support stronger positioning.
A third trend concerns procurement architecture and multinational alignment. Rising defense expenditures and soldier modernization programs across major allied forces are likely to sustain demand, but procurement decisions will increasingly emphasize standardization, interoperability, and lifecycle performance. Framework agreements, stock number recognition, and approval-list dynamics will continue to shape how products move from qualification to field adoption. For suppliers, this means that commercial success may depend as much on navigating procurement processes and demonstrating total value as on product innovation alone. For buyers, the implication is that supplier selection should account for qualification status, supply reliability, and support for multi-year logistics needs, not just unit specifications.
These trends carry inherent uncertainty. Budget cycles can shift procurement timing; standards may evolve in ways that change qualification requirements; and supply chain disruptions can affect delivery confidence. In addition, the balance between performance enhancement and cost control will remain a persistent pressure point. Companies and buyers alike should therefore treat the market's direction as promising but contingent, with success depending on adaptability, program execution, and the ability to translate technical advantage into procurement-relevant value.
PW Consulting
Strategic Actions for Decision Makers
Different stakeholder groups can extract actionable value from the current market dynamics by aligning their strategies with the forces most relevant to their positions.
-
For manufacturers, the priority is to strengthen the link between compliance, operability, and program execution. This means treating certification readiness as a strategic asset, investing in product architectures that support modularity and field adaptability, and building supply-chain resilience that protects delivery confidence. Differentiation is increasingly gained through the ability to meet military specifications reliably while also reducing logistical friction and enhancing mission usability. Companies should also evaluate where specialized capabilities—such as laser protection, advanced lens systems, or coalition-friendly configurations—can create stronger positioning than broad commodity competition.
-
For investors, the relevant question is not simply whether the market is expanding, but where value is being created and sustained. Market growth is supported by modernization programs and rising defense expenditures, but profitability and competitive durability depend on execution capability, certification access, and differentiation in higher-intensity segments. Attention should focus on organizations that demonstrate consistent program wins, credible qualification pathways, and product strategies that align with evolving procurement priorities. At the same time, risk awareness is essential, particularly around standards evolution, supply variability, and the concentration dynamics that shape entry barriers and competitive intensity.
-
For procurement and program leaders, the actionable insight is to evaluate protective eyewear not only as a compliance item but as a readiness enabler with total-cost implications. Selection criteria should account for approval status, supply reliability, optical performance in realistic conditions, compatibility with helmets and other equipment, and support for lifecycle management. Where programs span multiple forces or coalition environments, interoperability and standardization should carry additional weight. A disciplined evaluation framework that balances protection, usability, and logistical reliability can improve both field outcomes and procurement resilience.
The commercial stakes in this market are rising alongside its strategic importance. Decision makers looking to navigate segmentation detail, procurement pathways, competitive positioning, and forward scenario implications will find value in more granular research that ties market structure to actionable planning parameters. Further analysis of segment-specific dynamics, company-level capability assessments, and procurement-aligned forecasts can help translate these high-level trends into decisions that hold up under program scrutiny.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Eyewear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Computer on Wheels Market: Why 14.5% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Computer on Wheels Market
Market Landscape and Core Challenges
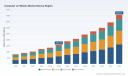
The global computer on wheels (COW) market has demonstrated robust expansion over the past half-decade, transitioning from a niche healthcare mobility segment to a mainstream component of clinical infrastructure. Market valuation placed the sector at approximately USD 1,577.16 million in 2025, reflecting consistent year-over-year growth from a base of USD 801.4 million in 2020. Forward-looking projections indicate a compound annual growth rate of 14.5 percent through 2032, with revenue anticipated to surpass USD 4 billion by the end of the forecast horizon. This trajectory underscores a structural shift rather than cyclical fluctuation, as healthcare delivery models increasingly prioritize bedside documentation, mobile diagnostics, and real-time electronic medical record access. Regional and product-type dynamics reveal a mature but still evolving demand pattern, with powered systems commanding the largest share of revenue while non-powered alternatives maintain relevance in cost-sensitive or space-constrained environments.
Despite the favorable growth trajectory, the industry faces several structural headwinds that will shape competitive positioning over the next decade. First, regulatory scrutiny around medical device compliance continues to tighten across multiple jurisdictions. Electrical safety, electromagnetic compatibility, and infection control standards now function as baseline requirements rather than differentiators, forcing manufacturers to embed compliance into design cycles rather than retrofitting existing platforms. Second, the integration of advanced battery and power management systems has introduced both an operational imperative and a supply chain vulnerability. Lithium iron phosphate packs with hot-swap capabilities have become the de facto infrastructure for sustained clinical operation, yet sourcing, lifecycle management, and replacement logistics remain fragmented across the vendor ecosystem. Third, labor cost pressures and nursing workflow inefficiencies are driving demand for mobility solutions, but procurement cycles in healthcare systems remain lengthy and highly sensitive to total cost of ownership calculations. Organizations must navigate the tension between immediate workflow gains and long-term capital justification, which can delay adoption in budget-constrained settings.
The market is also approaching a consolidation inflection point. Revenue concentration among the top three and top five participants indicates a moderately fragmented landscape with clear leadership clusters, but the presence of specialized regional suppliers and custom-configuration providers suggests that differentiation will increasingly hinge on integration depth, service networks, and lifecycle support rather than pure hardware specifications. Companies that treat COW deployments as static equipment purchases risk losing ground to competitors who position these systems as configurable, service-enabled platforms aligned with clinical workflow evolution.
Medical Computer Cart Market
Key Drivers Shaping Market Evolution
Several interdependent forces are accelerating demand and reshaping product requirements across the COW sector. At the technology frontier, the convergence of low-profile computing architectures, ruggedized enclosures, and modular battery ecosystems has redefined what mobile workstations can deliver at the point of care. Patented fast-swap battery technologies and lithium iron phosphate systems with hot-swap capabilities now enable continuous operation without downtime, which is critical for hospitals running extended clinical shifts. Manufacturers have responded by designing carts that accommodate third-party computing modules or integrate all-in-one medical-grade displays, allowing facilities to standardize on a mobility platform while retaining flexibility in processor selection, operating system configuration, and peripheral attachment. This modularity reduces replacement friction and extends asset longevity, aligning hardware refresh cycles with clinical IT roadmaps rather than forcing simultaneous upgrades across every deployment.
Policy and regulatory environments are acting as both a constraint and a catalyst. Healthcare computer on wheels systems must comply with medical device standards for electrical safety, electromagnetic compatibility, and infection control in hospital environments. Rather than treating these requirements as purely defensive, leading manufacturers are using compliance as a trust signal and a design anchor. Standardized certification pathways reduce procurement friction for health systems, while infection-control features such as seamless surfaces, antimicrobial coatings, and easily disinfected contact points are increasingly specified in tender documents. In parallel, broader digital health policies that encourage electronic medical record adoption and bedside data capture indirectly expand the addressable base for mobile workstations, since facilities investing in digital workflows require reliable, mobile access points that move with clinicians rather than anchor them to fixed terminals.
On the demand side, the most pronounced shift is the operational response to labor cost pressures and workflow inefficiency. Mobile computer on wheels reduce time spent by nurses walking to stationary terminals, supporting workflow efficiency in point-of-care documentation. This logistical benefit translates into measurable time savings during documentation, medication administration, and bedside rounding, which in turn influences purchasing decisions among nursing leadership and clinical operations teams. Beyond time savings, the expectation for real-time data access has raised the stakes for device reliability. Clinicians increasingly view mobile workstations as extensions of the clinical team rather than peripheral equipment, which elevates expectations for uptime, ergonomic design, and seamless docking or charging behavior. Facilities that have deployed sit-to-stand configurations or customizable workstation heights are reporting improved clinician acceptance, suggesting that ergonomics and usability have become as important as raw computing capability.
Supply chain and cost structure changes are also reshaping competitive dynamics. The shift toward battery-centric infrastructure has introduced a recurring component management dimension to what was historically a one-time capital purchase. Hot-swap battery packs and modular power systems create opportunities for repower services, warranty extensions, and lifecycle support contracts, converting some hardware revenue into longer-duration service relationships. At the same time, ISO-certified manufacturers with established export experience are expanding their footprint into global healthcare markets, increasing price and specification competition in regions where procurement teams balance clinical-grade requirements against budget constraints. This dynamic is encouraging both incumbents and new entrants to clarify their value propositions: whether they compete on integration depth, regional service coverage, cost efficiency, or specialized workflow configurations.
Competitive Landscape and Strategic Positioning
The competitive field is anchored by a group of U.S.-based manufacturers that have built recognizable positions around customization, battery innovation, and workflow alignment. Scott-Clark Medical has carved a niche around customizable healthcare computer on wheels and mobile computer carts, with powered systems featuring patented FMCPT battery technology optimized for point-of-care use in hospitals. This battery-led differentiation gives the company a tangible engineering narrative in procurement discussions where uptime and battery reliability are primary concerns. Altus Inc. competes across both powered and non-powered medical carts, offering battery-powered computer on wheels workstations designed for hospital EMR and patient care workflows. Its broader product span allows flexibility across budget tiers and deployment contexts, which is useful for health systems standardizing across multiple units or campuses. DTG Power emphasizes battery-powered workstation on wheels solutions and LFP battery systems, and notably positions repower services for existing carts from various manufacturers. This service-oriented angle extends the company's relevance beyond new equipment sales and into lifecycle support, an increasingly important consideration for facilities managing mixed-fleet environments.
Ergotron and Capsa Healthcare illustrate complementary strategic angles within the same ecosystem. Ergotron manufactures mobile computer carts and workstations on wheels for healthcare environments, frequently integrated with third-party battery and computing solutions, which positions the brand as a flexible platform partner rather than a closed-system vendor. Capsa Healthcare produces medical carts including computer on wheels and medication workstations designed for hospital point-of-care documentation and mobile computing, aligning product design directly with documentation and medication workflows. Cybernet and Teguar approach the market from the computing-hardware side, supplying all-in-one medical computers and rugged medical computers respectively, with configurations suitable for integration into computer on wheels carts in healthcare settings. Their strength lies in hardware durability, certification readiness, and compatibility with mobile cart ecosystems, making them relevant to buyers who prioritize compute reliability and environmental resilience. DataCart adds a further dimension with customizable workstations on wheels featuring sit-to-stand capabilities, targeting healthcare mobility and point-of-care applications where ergonomics and clinician posture are decision factors.
International participants are expanding the scope of competition. All Modul GmbH develops various models of computer on wheels from budget to high-end configurations, with customization options for European healthcare markets, which allows it to address both price-sensitive and specification-driven buyers in its region. ZHAOFA Technology operates as an ISO-certified manufacturer of hospital-grade computer on wheels and mobile workstations for global healthcare markets, and its continued offering of custom hospital-grade COW and WOW systems reflects a sustained focus on export-oriented, specification-adaptable production. Convergint Innovative Medical supplies workstations on wheels and computer on wheels solutions tailored for nursing workflows and simulation labs in healthcare, underscoring a workflow-and-training orientation that resonates with academic medical centers and simulation-based training environments.
The recent dynamics across these players point to a market that is simultaneously consolidating around a few recognizable leaders and fragmenting around specialized use cases. ZHAOFA's ongoing catalog emphasis on custom hospital-grade COW and WOW systems, supported by a decade of manufacturing experience, signals that configurable production remains a viable entry and growth path for established OEMs serving international buyers. Indurock's updated analysis of COW terminology, hospital applications, and future trends in mobile computer workstations for healthcare and logistics indicates that the category itself is being refined and communicated more precisely, which benefits buyers but also raises the bar for vendors to articulate clear use-case fit. Convergint's continued promotion of WOW/COW benefits for nurses and ongoing supply for healthcare simulation and clinical use highlights how workflow advocacy and training environments are becoming explicit demand channels, not just end-point deployments.
Strategically, the most successful players are those that convert hardware into a platform story. Battery technology, repower services, ergonomic configuration, infection-control design, and simulation-ready deployment all function as differentiators when they are tied to measurable clinical outcomes or operational savings. The market is therefore moving away from generic cart specifications toward solution-level competition, where vendors are evaluated on how well their mobile workstations fit nursing workflows, EMR integration expectations, and lifecycle management requirements. New entrants that bring clear workflow alignment, regional service capacity, or cost-efficient ISO-certified manufacturing can still gain traction, but they must do so by targeting a defined segment rather than competing broadly on price alone.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to define how the COW market evolves and where commercial opportunities concentrate. First, battery and power management will become the central lifecycle differentiator rather than a secondary feature. As lithium iron phosphate packs with hot-swap capabilities become standard expectations in clinical settings, competitive advantage will shift toward battery reliability metrics, replacement logistics, and repower or refresh services. Manufacturers and service providers that can standardize battery health monitoring, hot-swap training, and predictable replacement cycles will be better positioned to retain customers and expand into service-based revenue. The commercial implication is clear: mobility hardware will increasingly be evaluated as part of a managed power ecosystem, and procurement decisions will weigh total uptime and service coverage alongside initial unit economics.
PW Consulting
Second, workflow-integrated configurations will gain prominence over generic mobile carts. The push to reduce nursing walking time and improve point-of-care documentation is driving demand for sit-to-stand features, ergonomic adjustability, medication-specific workstation layouts, and simulation-ready setups. This trend favors vendors that can demonstrate how a specific cart configuration supports a documented clinical pathway, whether for bedside rounding, medication administration, or training environments. Companies that invest in workflow research, clinician feedback loops, and configurable options are likely to secure stronger preference in tenders, particularly in health systems that have moved beyond pilot deployments and are standardizing across multiple units. The opportunity here lies in packaging configuration flexibility with clear guidance on which layouts fit which workflows, reducing the decision burden for procurement teams and clinical leaders.
Third, the market will see continued pressure toward regional specialization and certified manufacturing footprints. ISO-certified manufacturers with global export experience are expanding reach into international healthcare markets, while regional customizers are refining offerings for local compliance expectations and procurement norms. This creates a dual dynamic: global scale players compete on integration breadth and service networks, while regional and cost-efficient manufacturers compete on specification adaptability and price-to-performance ratios. For commercial strategy, this means that buyers will increasingly choose between standardized global platforms and locally tailored configurations depending on their compliance environment, service expectations, and budget posture. The risk for vendors is that undifferentiated hardware becomes commoditized quickly, while the risk for buyers is that over-customization complicates maintenance and standardization across sites.
Computer On Module (COM) Market
A persistent uncertainty across these trends is the pace of health system capital cycles. Even when workflow benefits are well documented, procurement timelines can stretch, especially in environments where total cost of ownership justification must compete with other clinical priorities. Supply chain stability for battery components and the consistency of infection-control compliance across product lines will also influence adoption speed. Organizations that can align their value proposition with both clinical workflow gains and predictable lifecycle economics are best positioned to navigate these uncertainties.
Actionable Recommendations for Decision Makers
For manufacturers and solution providers, the priority is to move beyond product specifications and build a defensible workflow-and-lifecycle narrative. Differentiate around battery reliability, repower or refresh services, ergonomic configurations, and infection-control design, and make those claims traceable to documented clinical or operational benefits. Tailor go-to-market messaging to specific use cases rather than broad category language, since procurement teams increasingly evaluate mobile workstations against defined workflows and service expectations. Companies that can combine configurable hardware with predictable service coverage will be better positioned to protect margin and extend customer relationships over the asset lifecycle.
For investors evaluating exposure to this segment, focus on the durability of competitive advantages rather than headline growth alone.Assess whether a target company has genuine differentiation in battery technology, service infrastructure, workflow-aligned design, or regional manufacturing scale. Examine the balance between one-time hardware sales and longer-duration service potential, since lifecycle support and repower capabilities can materially affect recurring revenue quality. Also pay attention to compliance readiness and certification positioning, as these factors influence procurement speed and customer retention in regulated clinical environments. Companies whose growth depends primarily on price competition without workflow or service differentiation carry higher exposure to margin compression as the category matures.
For healthcare procurement teams and clinical operations leaders, the most effective approach is to evaluate mobile workstations as configurable platforms integrated into documented workflows, not as interchangeable equipment purchases. Standardize on core requirements for electrical safety, electromagnetic compatibility, infection control, and battery uptime, then use configuration flexibility to address department-specific needs such as sit-to-stand ergonomics, medication workstation layouts, or simulation lab use. Where possible, prioritize vendors that can support mixed-fleet environments, provide clear battery lifecycle management, and offer training or workflow guidance for clinicians. This reduces operational friction and helps ensure that mobility investments translate into measurable time savings and documentation efficiency rather than unused capacity.
Given the speed at which battery standards, compliance expectations, and workflow preferences are evolving, detailed segment-level data and customized scenario planning remain valuable for precise decision making. Organizations preparing capital plans, product roadmaps, or procurement strategies can benefit from a fuller breakdown of regional demand patterns, product-type economics, end-user dynamics, and company-level benchmarking to ensure that commitments are aligned with the most current market structure.
For detailed analysis of this topic, please visit the official page: Worldwide Computer on Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Enclosed Track Conveyors Market: How 5.85% CAGR Drives 2032 Expansion Beyond Scale
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Enclosed Track Conveyors Market
Market Overview: Current Landscape and Core Challenges
The global enclosed track conveyor industry enters the late 2020s as a mature yet steadily expanding segment within material handling and industrial automation. Valued at approximately USD 784.5 million in 2025, the market has demonstrated consistent growth from its 2020 baseline, with projections indicating a trajectory toward USD 1.17 billion by 2032. This expansion reflects a compound annual growth rate of 5.85 percent across the forecast horizon, signaling durable demand rather than cyclical volatility. The sector's resilience stems from its foundational role in overhead material transport, where enclosed track systems offer a compelling balance of load capacity, spatial efficiency, and operational safety compared to open I-beam alternatives.
However, growth trajectories are not without friction. Three structural challenges currently shape the industry's evolution. First, supply chain volatility in specialized steel profiles and precision chain components continues to influence lead times and system pricing. Enclosed track conveyors depend on engineered track geometries and hardened chain links that require controlled metallurgical processes, making upstream material availability a persistent operational variable. Second, the regulatory environment is tightening around safety and dust exposure, with updated standards introducing new compliance requirements for design, inspection, and maintenance protocols. Manufacturers and end-users must now navigate more rigorous documentation and installation verification, which raises upfront engineering costs but also creates a barrier that favors established players with mature quality systems. Third, the market faces a integration paradox: as facilities pursue smarter, data-driven operations, legacy enclosed track installations often lack native connectivity, forcing operators to weigh retrofit investments against full system replacements. This tension between operational continuity and digital upgrade paths defines much of the current procurement discourse.
Geographically, the market exhibits a clear concentration pattern, with the Asia Pacific and North America regions accounting for the largest revenue shares, followed by Europe. This distribution reflects differing industrial maturation levels, automotive and electronics manufacturing footprints, and logistics infrastructure investment cycles. Application demand remains anchored in automotive assembly and industrial finishing, while e-commerce fulfillment and food processing continue to gain incremental share as hygiene standards and flexible layout requirements intensify. The competitive structure remains moderately fragmented, with the top three suppliers capturing roughly one-third of total revenue and the top five approaching half, leaving substantial room for regional specialists and technology-differentiated entrants.
Key Demand Drivers and Structural Shifts
Technological Innovation and Modular System Design
The most visible driver of market expansion lies in the ongoing refinement of modular, enclosed track architectures that prioritize installation flexibility and maintenance efficiency. Traditional overhead conveyor deployments often required extensive structural modification and long commissioning windows. Newer system designs emphasize standardized trolley interfaces, quick-swap chain segments, and pre-engineered bend radii that reduce on-site fabrication. This modularity aligns directly with the operational reality of modern manufacturing floors and distribution centers, where production lines must be reconfigured for product mix changes, seasonal volume swings, or footprint optimization. Companies that have showcased integrated demonstrations combining enclosed track conveyors with robotic handling and automated order fulfillment illustrate how mechanical material transport is increasingly treated as a component within broader automation ecosystems rather than a standalone utility. The commercial implication is clear: system value is shifting from pure load-moving capability toward integration readiness, serviceability, and layout adaptability.
Policy, Safety Standards, and Compliance Dynamics
Regulatory and standards activity is reshaping procurement criteria across the sector. Updated safety frameworks for conveyors and related equipment now extend more explicitly to enclosed track designs, introducing provisions that address dust hazards, inspection frequency, and operational verification. These requirements do not merely add bureaucratic steps; they alter the total cost of ownership calculus. Facilities operating in finishing, powder coating, food processing, and light industrial environments must account for contamination control, surface protection, and worker exposure in ways that favor enclosed configurations over exposed alternatives. At the same time, compliance pressure rewards suppliers with documented quality management, traceable component sourcing, and field service networks capable of supporting recurring inspection cycles. The trend effectively raises the floor for market participation while creating a differentiation axis for vendors that can package safety compliance, documentation, and lifecycle support into a single procurement proposition.
Demand-Side Shifts in Manufacturing and Logistics
End-user behavior is evolving under the combined influence of labor availability pressures, throughput expectations, and facility design priorities. In automotive and heavy assembly environments, enclosed track systems continue to serve as reliable work-in-process transporters that keep floor space clear and reduce manual handling risk. In finishing and coating applications, the enclosed nature of the track helps contain overspray, protect moving components, and support cleaner_process environments. Meanwhile, e-commerce and logistics operations increasingly evaluate overhead conveyance not only for bulk movement but also for sequenced order picking, sorting integration, and ergonomically optimized workstations. This broadening application base reduces dependence on any single vertical and creates cross-sector demand for systems that can be scaled in span, speed, and load rating without major redesign. The practical outcome is a more diversified demand profile, where flexibility and hygiene considerations often compete with pure cost-per-foot arguments.
Supply Chain and Cost Structure Considerations
Cost dynamics are being reshaped by the interplay of raw material sourcing, component specialization, and service expectations. Enclosed track systems rely on engineered steel tracks, precision chains, trolleys, and drive units, meaning that fluctuations in metal pricing, motor availability, and machining capacity reverberate through project quoting and delivery schedules. At the same time, customers are increasingly sensitive to installed cost, downtime during changeovers, and long-term maintenance burden. This environment favors suppliers that can offer standardized component libraries, regional inventory positioning, and predictive maintenance guidance. It also encourages end-users to evaluate lifecycle economics more rigorously, weighing initial capital expenditure against spare parts availability, technician training, and the ability to expand or reconfigure the system without replacing the entire track infrastructure. In effect, cost competition is moving from unit price to reliability, lead time, and upgrade-option value.
Competitive Landscape and Strategic Positioning
The competitive field combines long-established North American manufacturers with international component suppliers and regional specialists. This mix creates a layered environment where incumbents compete on system breadth, engineering support, and installed-base service, while newer or regional players compete on price, niche load ratings, and localized deployment agility.
PW Consulting
Among the established names, companies with long track records in enclosed track monorail systems emphasize durability, modular installation, and application breadth. Profiles from firms originating in the mid-twentieth century often highlight standardized configurations that simplify specification for auto-body shops, manufacturing floors, and receiving areas. Their differentiation rests on proven uptime narratives, extensive field references, and the ability to offer power-only, power-and-free, and towline variations within a common design language. This breadth allows them to address a wide range of load profiles and throughput requirements while maintaining consistent spare-parts logistics.
Other leading players focus on capacity tiers and integration readiness. Some offer medium-capacity solutions tailored for tight spaces, while others provide heavy-duty variants or over-under configurations designed for large-volume production at a favorable cost position versus traditional I-beam systems. A distinct subset of competitors centers on component-level strength, supplying chains, trolleys, and specialty hardware to system builders and end-users alike. This component-focused model is strategically important because it embeds the supplier within multiple system architectures, creating recurring demand even when full-system projects fluctuate.
Recent activity underscores how competition is shifting toward integration and application-specific demonstrations. Public showcases combining enclosed track conveyors with robotic handling for carton movement and order fulfillment point to a market where mechanical transport is increasingly validated within end-to-end automation scenarios. At the same time, catalog and product updates emphasizing standard components with free-running trolleys for lower-cost overhead applications indicate continued segmentation between value-oriented installations and engineered, higher-capacity systems. The competitive signal is that suppliers are pursuing both ends of the spectrum: premium integration for complex workflows and standardized affordability for simpler overhead transport needs.
Worldwide Enclosed Torque Motor Market
Future Outlook: Trends Shaping the Next Three to Five Years
Several interdependent trends are likely to define market direction through the early 2030s. First, integration depth will increase as facilities seek overhead conveyance that communicates with broader control architectures. This does not necessarily mean every installation becomes highly automated, but it does suggest that compatibility with sensors, programmable logic, and data collection layers will become a more frequent selection criterion. Systems that can be instrumented for throughput monitoring, fault detection, and maintenance scheduling will hold a growing advantage in environments where downtime is costly and changeover frequency is high.
Second, hygiene and contamination control will continue to pull demand toward enclosed configurations in finishing, food-adjacent processing, and clean manufacturing contexts. As environmental and operational standards tighten, the enclosed track's ability to shield chains and trolleys from particulates, overspray, and incidental contamination will be valued not only for equipment longevity but also for process consistency. This trend favors suppliers that can articulate cleaning protocols, material compatibility, and service practices aligned with regulated or high-purity environments.
Third, regional capacity and supplier diversification will likely expand, particularly as end-users seek shorter lead times, localized service, and reduced exposure to single-region supply disruptions. Asia Pacific's substantial revenue presence and the presence of component manufacturers in Taiwan and India indicate an ecosystem capable of supporting both full-system projects and component-level supply. The opportunity for new entrants and expanding incumbents lies in pairing regional manufacturing responsiveness with reliable engineering specifications and compatible interface standards.
Potential risks remain. Steel and motor cost volatility can compress margins and delay projects, especially for engineered systems with long quote-to-delivery cycles. Regulatory updates may raise compliance costs in the near term, particularly for operators retrofitting older installations. In addition, if automation budgets soften in key verticals, procurement may shift toward incremental upgrades rather than full replacement, pressuring suppliers to offer flexible expansion paths and retrofit-compatible components.
Strategic Actions for Decision-Makers
For manufacturers and automation engineers, the priority should be to evaluate enclosed track systems not only on load capacity and footprint, but also on integration readiness, service access, and reconfiguration flexibility. Favor designs that allow span adjustments, trolley interchangeability, and straightforward inspection access, and align component selection with the facility's anticipated product-mix volatility.
For investors and corporate development teams, the opportunity lies in identifying suppliers that combine application breadth with credible service networks and component-level repeatability. Companies that can support multiple verticals while maintaining standardized interfaces and documented compliance practices are better positioned to capture demand as facilities modernize incrementally rather than replacing systems wholesale.
Enclosed Belt Conveyor Market
For procurement and operations leaders, total cost of ownership should be assessed across lead time, spare-parts compatibility, maintenance burden, and upgrade options rather than initial installed price alone. Where hygiene, dust control, or turnover frequency are material, enclosed track configurations warrant explicit comparison against open alternatives, with due attention to compliance documentation and service-response capability. Given the pace of standards updates, integration expectations, and regional supply shifts, more granular segmentation data and tailored scenario analysis can help decision-makers narrow specification choices and time investments more effectively. Readers seeking deeper breakdowns by application profile, regional deployment patterns, and company-level positioning can review the full PW Consulting market report for detailed segmentation metrics and actionable recommendations aligned to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Enclosed Track Conveyors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Egg Packing Machinery Market: Why Automatic Systems and 5.43% CAGR Redefine Supply Chains
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Egg Packing Machinery Market
1. Market Overview and Core Challenges
The global market for egg packing machinery has demonstrated consistent expansion over the past half-decade, with revenue estimates indicating a trajectory from approximately $572.25 million in 2020 to a projected $1.079 billion by 2032. Driven by a compound annual growth rate of 5.43 percent during the 2026-2032 forecast period, the sector reflects a maturation phase where efficiency, hygiene, and scalability dictate procurement decisions rather than mere capacity expansion. The current market size of roughly $745.5 million in 2025 underscores a robust foundation, yet the path forward is not without structural friction. Industry participants must navigate a landscape where volume growth increasingly depends on operational excellence rather than simple market penetration.
One of the most pressing challenges facing the sector is the persistent tension between labor availability and automation requirements. Agricultural and egg processing facilities across multiple regions are grappling with workforce constraints, which directly impact manual grading and packing lines. This labor shortage is not merely a temporary cyclical issue; it represents a structural shift that forces producers to reconsider their reliance on manual processes. The imperative to reduce manual handling and operational costs is accelerating the transition toward automated solutions, yet the capital expenditure required for such transitions can be a barrier for smaller operators who lack the cash flow to invest in high-throughput systems without clear ROI timelines.
Tray Sealing Machines Market
Regulatory pressures form a second critical pivot point. Stringent food safety mandates, particularly those focused on hygiene, Salmonella control, and pasteurization protocols during egg handling, are reshaping equipment specifications. Compliance is no longer optional, and machinery that lacks enhanced sanitary design faces obsolescence risk. Manufacturers and end-users alike must account for these regulatory demands in their capital planning, as retrofitting older lines or investing in new systems with compliant materials—such as stainless steel components for egg contact areas—adds complexity to procurement cycles and total cost of ownership calculations.
A third challenge lies in balancing throughput demands with product integrity. The macro trend of increasing global demand for eggs and processed egg products is pushing facilities to adopt machines capable of handling 10,000 to 60,000 eggs per hour. However, higher speeds must not compromise gentle handling, a requirement that remains paramount for table eggs and breeding stock. Equipment that can deliver both velocity and care is in high demand, but engineering such dual-capability systems requires sophisticated modular designs and precise control systems. Companies that fail to align their product offerings with this balance risk losing ground to competitors who can demonstrate verifiable gentle handling at scale.
2. Key Drivers of Market Growth and Transformation
Technological innovation stands as the primary catalyst reshaping the competitive dynamics of egg packing machinery. Advances in sensor technology, vision systems, and automated sorting algorithms are enabling machines to achieve higher accuracy in grading while minimizing breakage rates. Modular designs have become a hallmark of modern equipment, allowing producers to scale their operations incrementally rather than committing to monolithic line replacements. This flexibility is particularly valuable in an environment where farm sizes and processing volumes can fluctuate due to market conditions, avian influenza outbreaks, or shifting consumer preferences. The ability to integrate fixed or variable speed options, mobile units, and adaptable packing configurations means that machinery can evolve alongside the business, reducing the risk of stranded assets.
The policy and regulatory environment is exerting a profound influence on equipment selection and deployment. Beyond the baseline hygiene and food safety requirements, there is an increasing expectation for traceability and data capture within packing lines. Automated systems that log grading decisions, track egg batches, and integrate with broader farm management software are gaining traction as producers seek to demonstrate compliance and optimize operational insights. Regulations that mandate specific sanitation protocols for wash and packing lines also drive demand for materials and designs that facilitate rapid cleaning and reduce contamination risks. Equipment manufacturers that proactively align their R&D with these regulatory trajectories position themselves as partners in compliance rather than mere vendors of hardware.
On the demand side, consumer and enterprise behavior is shifting in ways that favor processed and value-added egg products alongside traditional table eggs. This diversification requires packing and grading equipment that can handle multiple formats, from standard trays to specialized packaging for liquid egg or further processing. Medium and large farms, as well as dedicated egg processing plants, are increasingly looking for integrated solutions that bridge grading, washing, printing, and packing into a cohesive workflow. The pursuit of throughput efficiency is not solely about volume; it is about consistency, reduced waste, and the ability to meet fluctuating order profiles without sacrificing quality. Enterprises that can demonstrate reliable performance across varied product streams are capturing a larger share of capital expenditure budgets.
PW Consulting
Supply chain and cost structure dynamics also play a pivotal role. The reliance on stainless steel for components in contact with eggs ensures hygiene and durability, but material costs and availability can influence pricing and lead times. Furthermore, the concentration of manufacturing capabilities in certain geographic clusters means that logistics, customs, and local support networks become critical considerations for buyers. Companies that can offer localized service, spare parts availability, and rapid response to downtime minimize the operational risks associated with global procurement. At the same time, cost pressures are driving a search for machines that deliver higher throughput per unit of labor and energy, reinforcing the value proposition of automation even in contexts where labor is available but expensive.
Recent industry activities illustrate how these drivers converge in practice. Participation in major trade exhibitions such as IPPE 2026, which featured extensive exhibits on poultry and egg processing equipment with record attendance and floor space, signals the sector's vitality and the intensity of innovation dissemination. Similarly, manufacturers showcasing their latest grading and packing machines at regional events like CAHE 2026 in Chengdu highlight the growing importance of Asian markets and the desire to demonstrate capabilities directly to a diverse audience of producers and integrators. These events serve as barometers for where technology, demand, and regional growth intersect, offering tangible evidence of the market's directional shifts.
3. Competitive Landscape and Leading Strategies
The competitive environment in egg packing machinery is characterized by a mix of established multinational players and specialized regional manufacturers, with a concentration ratio that suggests a moderately consolidated structure. Leading firms differentiate themselves through a combination of product breadth, technological sophistication, and service ecosystems. Companies that offer automated systems spanning from small farm applications to full-scale production lines with gentle egg handling and modular designs are well-positioned to capture value across diverse customer segments. The ability to provide high-capacity automated packing lines and integrated solutions allows leaders to address the throughput demands of large operations while maintaining the flexibility to adapt to varying egg types and packaging formats.
Strategic positioning among top competitors often hinges on the balance between automation level and operational practicality. Some manufacturers specialize in compact, versatile automatic packing machines that emphasize modularity, mobility, and fixed or variable speed options, catering to facilities that require reliable performance without excessive footprint or complexity. Others focus on gentle egg handling and packing for table eggs in trays, offering both semi-automatic and automated packers suited for layers and breeders. This segmentation of strengths means that buyers must evaluate not only technical specifications but also the alignment of a supplier's core competencies with their own operational profile, growth plans, and regulatory obligations.
Regional diversity among manufacturers adds another layer to the competitive dynamics. Firms based in Europe and North America often emphasize advanced automation, integration with broader poultry systems, and compliance with stringent food safety frameworks, while manufacturers from Asia and other emerging regions frequently compete on cost efficiency, rapid deployment, and complete automated processing and packing lines that cover grading, washing, printing, and separation. This divergence creates opportunities for cross-regional learning and partnership, as well as potential friction in terms of perceived quality, support infrastructure, and long-term reliability. Buyers increasingly weigh total cost of ownership, including service availability and spare parts logistics, against upfront pricing, which can shift the competitive advantage toward suppliers with strong local presence and responsive after-sales networks.
The market is also witnessing evolutionary trends in consolidation and new entry. Larger players with integrated poultry and egg production system portfolios, including egg handling and packing solutions, are well-placed to offer end-to-end value propositions that reduce integration risk for customers. At the same time, specialized firms focusing on egg processing equipment with capabilities supporting packing and sorting lines for food industry applications are carving niches around specific processing needs, such as pasteurization readiness or specialized tray configurations. New entrants and expanding regional players continue to challenge incumbents by targeting underserved segments, leveraging cost structures, and adopting proven technologies to accelerate time-to-market. In this environment, the ability to demonstrate consistent performance, gentle handling, and regulatory compliance becomes a key differentiator, as does the capacity to provide modular, scalable solutions that grow with the customer's business.
The competitive landscape is further shaped by the emphasis on hygiene and material standards. Equipment that prioritizes stainless steel components for egg contact areas not only meets sanitary design expectations but also signals durability and lower long-term maintenance burdens. Suppliers that embed these material choices into their core engineering philosophy, and that can articulate the operational and compliance benefits clearly, build trust with procurement teams that must justify capital investments against both financial and risk-management criteria. The interplay of these factors suggests a market where differentiation is increasingly derived from integrated technology, service reliability, and the ability to navigate the intersection of throughput, hygiene, and flexibility.
4. Future Trends and Strategic Outlook (2026-2032)
One of the most significant trends likely to define the next three to five years is the deepening integration of automation with data-driven management. As labor constraints persist and regulatory scrutiny intensifies, packing lines will increasingly function as nodes within broader digital ecosystems. Grading and packing equipment will be expected to capture granular operational data, support traceability requirements, and interface with farm and processing management platforms. This shift creates commercial opportunities for manufacturers and integrators who can offer seamless connectivity, analytics dashboards, and predictive maintenance capabilities, while also posing a risk for those whose products remain isolated hardware solutions without clear pathways to data integration.
A second trend is the continued push toward higher throughput combined with uncompromising gentle handling. Demand for eggs and processed egg products is expected to remain robust, and facilities will seek machines that can process 10,000 to 60,000 eggs per hour without elevating breakage or compromising hygiene. Innovation in conveyance, cushioning, and speed control will differentiate suppliers, and end-users will reward systems that balance speed with product protection. The opportunity here lies in engineering and marketing solutions that provide verifiable performance metrics, enabling buyers to model ROI based on reduced waste and higher quality output. A risk to monitor is the potential for over-optimization on speed at the expense of handling quality, which can erode trust and lead to costly retrofits or replacements.
Third, regional demand dynamics will continue to reshape where growth is most pronounced and where competitive pressure intensifies. Markets with expanding medium and large farm operations, as well as dedicated processing plants, will drive demand for integrated, high-capacity lines, while smaller or more cost-sensitive regions may favor semi-automatic or modular solutions that allow incremental upgrades. This divergence creates opportunities for tailored go-to-market strategies, localized support models, and product configurations that match regional regulatory and operational contexts. A key uncertainty is the pace of regulatory evolution and the extent to which hygiene and safety mandates accelerate automation adoption across all segments, which could compress the window for semi-automatic solutions in certain markets.
5. Strategic Considerations for Decision-Makers
For manufacturers, the priority is to sustain investment in modular, sanitary, and data-ready designs that can serve a spectrum of farm sizes and processing formats. Aligning R&D with the dual imperatives of throughput and gentle handling, while ensuring compliance with evolving hygiene standards, will strengthen competitive positioning. Building robust service and parts networks, along with clear communication of material choices such as stainless steel for critical components, can differentiate offerings in a market where total cost of ownership matters as much as initial price.
High Speed Packaging Machine Market
For investors, the landscape suggests selective opportunities in companies that demonstrate scalable technology platforms, strong regional presence, and the ability to integrate packing solutions with broader poultry system portfolios. Concentration dynamics indicate that consolidation and partnership activity may continue, and due diligence should weigh service capabilities, regulatory alignment, and the flexibility of product lines to adapt to shifting demand patterns. Tracking exhibition activity and product launches at major industry events can provide early signals of innovation direction and regional focus.
For purchasers and procurement teams, the decision matrix should extend beyond headline throughput figures. Evaluating gentle handling performance, hygiene design, modularity, and the supplier's ability to support compliance and data integration will reduce long-term operational risk. Engaging with suppliers that can demonstrate reliable performance across varied product streams, and that offer clear pathways for incremental capacity expansion, helps balance immediate needs with future growth. For those seeking granular segmentation data and tailored strategic recommendations, the full research report provides detailed breakdowns across regions, types, and applications, along with scenario analysis to support capital planning and competitive positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Egg Packing Machinery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com